
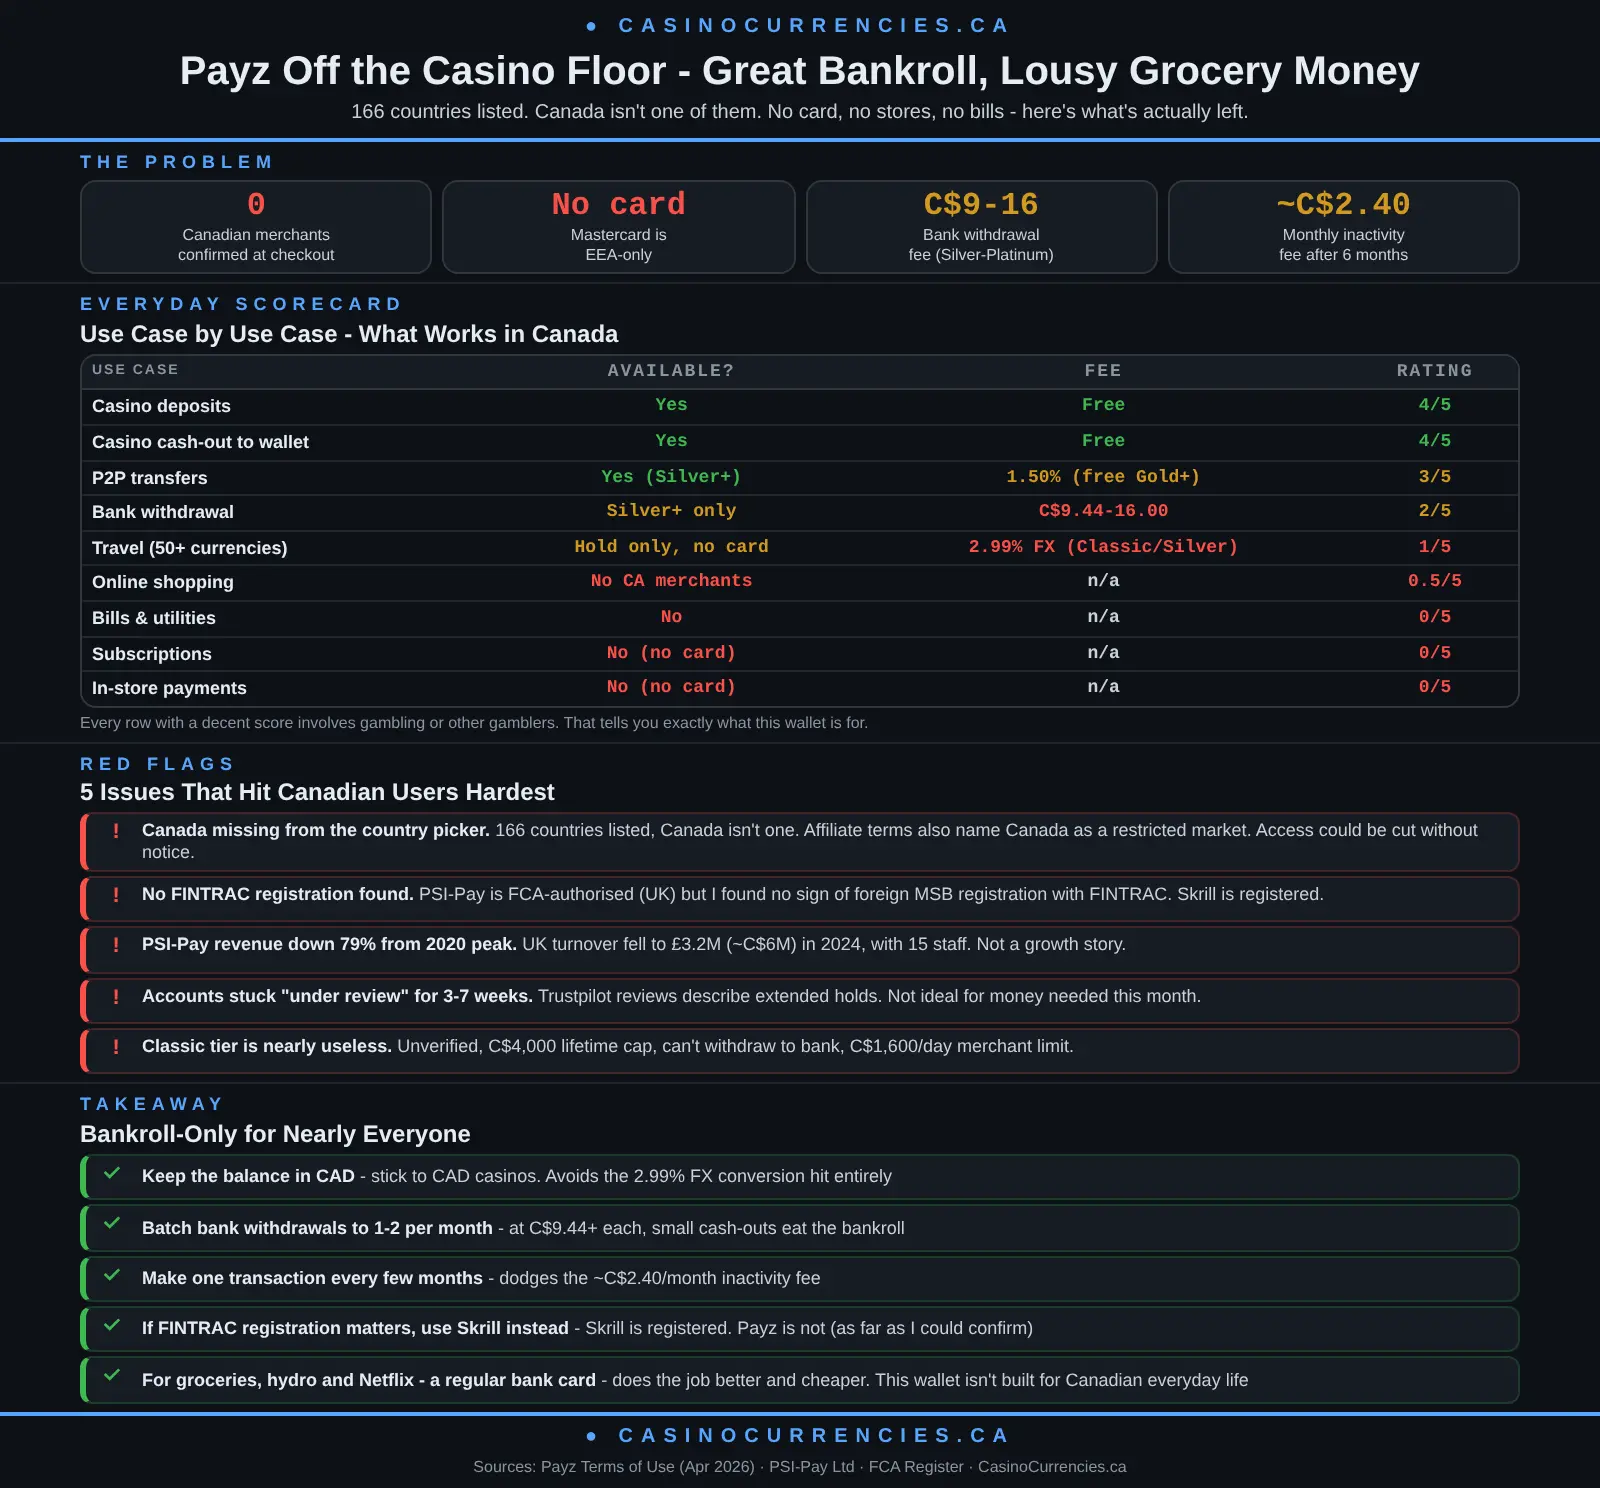
Payz lists 166 countries in its own country picker. Canada isn't one of them. That detail colours everything below, because a wallet that may not take new Canadian sign-ups is a hard sell for groceries and hydro bills.
I've already covered the bankroll side in my guide to ecoPayz casinos Canada players can still use. This piece asks something else. Once the casino money's sorted, can the wallet pull its weight anywhere else? I went through the official fee pages, the help centre and the terms of use (in force since 23 April 2026) to find out.
A quick note on numbers. Fees are set in euros, so I've converted at 1 EUR = C$1.60. Rates move, so treat every C$ figure as close rather than exact.
Short answer: is Payz worth having outside casino play?
Mostly, no. For Canadians, this e-wallet is a bankroll tool and not much else. The prepaid Mastercard goes only to residents of the European Economic Area (EEA). So there's no card for tapping at a till, paying Netflix or booking a hotel abroad.
What's left is wallet-to-wallet transfers and holding a few currencies. Both work. Both come with strings, and Canada's status itself is wobbly - more on that below.
Where can I actually use Payz day to day in Canada?
I split this into the places most Canadians actually spend money. Here's the honest breakdown.
Online shopping
I couldn't confirm a single Canadian non-gambling merchant that takes the wallet at checkout. Maybe one exists somewhere. But I didn't find it, and the merchant network I could see here is basically gambling sites.
Bills and subscriptions
Hydro, phone plans, Netflix, Spotify - they all bill a card or pull from a bank account. Without a card, there's nothing to type into the payment box. Card products are EEA-only, so Canadians can't get a physical or virtual one.
Peer-to-peer transfers
This is the one everyday feature that genuinely works. Transfers between Payz users are instant, according to the company. The catch is that sender and receiver both need Silver or higher, which means passing ID checks first. Fees run 1.50% (minimum about C$2.40) on Silver and drop to zero on Gold and up, per third-party fee guides.
So splitting a cottage rental only works if every friend holds a verified wallet too. Outside poker and casino circles, that's rare.
Travel
The wallet supports 50+ currencies and up to 10 currency accounts. Sounds handy for a trip to Europe - until I remember there's no card to spend those euros with. Converting inside the wallet also costs 2.99% on Classic and Silver.
In-store
No card, no tap. In-store use simply isn't on the menu for Canadian residents.
Everyday use cases: available or not?
Here's the full picture in one table. Ratings are my own call, based on access, cost and how often the feature would realistically get used.
| Use case | Available to Canadians? | Fees | My rating |
|---|---|---|---|
| Deposits at offshore casinos | Yes, at sites that list it (rarely Ontario-licensed ones) | Free, per third-party sources | 4/5 |
| Casino cash-out to wallet | Yes | Free, per third-party sources | 4/5 |
| Online shopping (non-gambling) | No verified Canadian merchants | n/a | 0.5/5 |
| Bills (hydro, phone) | No | n/a | 0/5 |
| Subscriptions (Netflix, Spotify) | No - cards are EEA-only | n/a | 0/5 |
| Peer-to-peer transfers | Yes, Silver+ on both ends | 1.50% (min. C$2.40) on Silver; free on Gold+ | 3/5 |
| Travel spending | Can hold 50+ currencies, but no card to spend them | FX 2.99% Classic/Silver, 1.49% Gold/Platinum, 1.25% VIP | 1/5 |
| In-store payments | No | n/a | 0/5 |
| Withdrawal to a Canadian bank | Silver or higher only | C$9.44–16.00 (Silver to Platinum) | 2/5 |
The pattern's obvious. Every row with a decent score involves gambling or other gamblers. For the casino-side scores in detail, my ecoPayz casino reviews go deeper.
What perks does Payz bring to everyday money?
I didn't find a points or cashback scheme for Canadian users on any page I checked. The "rewards" are cheaper fees as the account climbs tiers. Still, a few perks are real:
- Card privacy. The casino sees a wallet ID, never the card number. That's one less database holding bank details.
- A hard budget wall. Keeping the bankroll in a separate wallet makes monthly spend on the grind easy to track. Truth is, this is the perk I rate highest.
- Tier discounts. The Classic vs Gold gap is huge. Classic is unverified, capped at C$4,000 lifetime and can't cash out to a bank. Gold cuts FX to 1.49% and makes transfers free. But a third-party guide says it needs roughly C$16,000 in eligible deposits per quarter.
- Multi-currency balances. Up to 10 currency accounts. Holding CAD skips the 2.99% conversion hit when the casino balance is also in CAD.
- Ring-fenced funds. Customer money is kept separate from company money.
Is Payz safe to park money in?
On paper, mostly. PSI-Pay Ltd, the company behind the brand, is an FCA-authorised e-money institution (FRN 900011) and a Principal Member of Mastercard, per the official About page. The gap is Canadian oversight. I found no sign that PSI-Pay is registered with FINTRAC as a foreign money services business. Skrill is.
That alone tips the Payz vs Skrill call toward Skrill for most Canadians. And 2026 Trustpilot reviews describe accounts stuck "under review" for 3 to 7 weeks - not ideal for money needed this month.
Where does it fall short in real life?
Plenty of places. These are the ones that bite hardest:
- Canada's status is unclear. Canada is missing from the country list on payz.com. The company's own affiliate terms also name Canada as a market affiliates must not promote in - awkward for a site like mine, and I'd rather say it than bury it. Clause 24.10 lets the company restrict any country without notice. Around April 2022, a live-chat agent told one Ontario user that online merchant payments were temporarily blocked.
- No card. Covered above, but it kills most everyday use on its own.
- Bank cash-out costs. Withdrawing to a bank runs C$9.44–16.00 on Silver to Platinum, and correspondent bank charges can stack on top. Arrival time is another unknown. My own landing page says up to five business days, and I'm still confirming that figure.
- Inactivity fee. About C$2.40 a month once the account goes quiet. The company says it starts after 6 months; another source says 12. The sources conflict, so I'd assume six.
- Classic limits. Merchant payments on Classic max out at about C$1,600 a day, under that C$4,000 lifetime cap.
- A shrinking business. PSI-Pay's UK turnover fell to £3.2 million (about C$6 million at C$1.85 per pound) in 2024. That's down roughly 79% from its 2020 peak, with 15 staff. Those accounts may not include the Cyprus arm, but it's hardly a growth story.
Verdict: everyday wallet or bankroll-only?
Bankroll-only, for nearly everyone. The Payz fees on everyday tasks are either steep or beside the point, because most of those tasks aren't possible to begin with.
Worth keeping for wider use
- Players who've already passed verification and hold Silver or higher outside Ontario.
- Poker groups or casino regulars who settle up wallet to wallet.
- Anyone close to Gold, where FX drops to 1.49% and transfers cost nothing.
Bankroll-only, at most
- Anyone who wants a card for bills, shopping or travel.
- Ontario residents.
- New sign-ups - Canadian access is unconfirmed.
- Players who want confirmed FINTRAC registration. Skrill fits better there.
The practical takeaway
If I were running a wallet today, here's how I'd handle it:
- Keep the balance in CAD and stick to casinos that also run in CAD. No 2.99% hit.
- Batch bank withdrawals into one or two a month. At C$9.44 or more each, small cash-outs eat the bankroll.
- Make at least one transaction every few months to dodge the inactivity fee.
- Read the bonus terms before any casino deposit. E-wallet deposits are often excluded from welcome offers.
- Test a small cash-out first. Casino-to-wallet usually lands within hours of approval - the only withdrawal time I'd plan around.
For brands that still list the wallet, my shortlist of online casinos that accept Payz tracks which ones still take it. For groceries, hydro and Netflix, a regular bank card does the job better and cheaper.