
Here's a bit of trivia that trips people up. The Canadian processor behind most casino Interac buttons doesn't even own the obvious .com. That address belongs to an unrelated Japanese company, which launched its site on August 1, 2024. The real Gigadat lives at gigadatsolutions.com, and most Canadians only ever meet it at a casino cashier.
So I asked a blunt question. Can the tool that moves my bankroll also handle groceries, rent splits or the hydro bill? I went through six everyday jobs and stuck to facts I could back up. The answer isn't flattering, but it's useful.
Is Gigadat Worth Having Outside Casino Play?
Short answer: no. And not because it's bad. There's simply nothing to “have”. Gigadat isn't a consumer e-wallet. There's no account to open, no balance to fund, no app and no card.
It sits in the middle, between a merchant and the player's own bank, and moves money over Interac. Shoppers only see it when a merchant builds it into checkout. Outside gambling and one fintech app, I couldn't confirm a single named retail or travel merchant using the Gigadat payment processor.
That makes it a bankroll tool, full stop. Since the cashier is where it lives, the smart move is picking a good cashier. My reviews of Canadian casinos that take Gigadat rank them on payout speed and limits.
Where Can I Actually Use Gigadat in Everyday Life in Canada?
In its merchant pitch, the company names six target sectors. They are digital goods, retail, eSports, social gaming, financial services, and travel and tourism. That's the sales sheet. Here's how each everyday job plays out for a regular Canadian with a chequing account.
Online shopping: only where the store plugs it in
Shoppers can't pick this processor on their own. If a store routes Interac through it, a hosted page opens and the buyer approves the payment inside their own bank. That's the same Gigadat online banking flow casino players already know. I found no verified big-name retailer using it, though.
Bills: no
Hydro, phone and property tax bills go through each bank's own bill-pay menu. There's no way to point Gigadat at a utility. It only moves money for merchants that have signed up with it.
Peer-to-peer transfers: no
Paying a roommate back? Plain Interac e-Transfer from the banking app does that job. A Gigadat Interac e-Transfer only exists when a merchant generates one — either a deposit address with a unique reference ID, or a Request Money prompt approved inside the player's bank.
Subscriptions: no
Interac is push-only. The payer sends money, and nobody can pull it later. Streaming or gym memberships need an automatic pull, so this model can't handle them.
Travel: on paper only
Travel and tourism sits on the official sector list. But I couldn't confirm one airline, hotel or booking site that uses it. It's also Canada-only and settles in CAD, so it's no help once a trip crosses the border. A June 2024 tie-up with PayDo, a UK e-money firm, only brings PayDo's business clients into Canadian bank transfers. It doesn't take the processor abroad.
In-store: no
No card, no tap-to-pay, no Apple Pay or Google Pay. At a till, it simply doesn't exist.
The one real non-casino example
MuchBetter, the fintech wallet, uses Gigadat to process its e-Transfer withdrawals. That's the most “everyday” brush most people will get — cashing out of an app, not paying for anything.
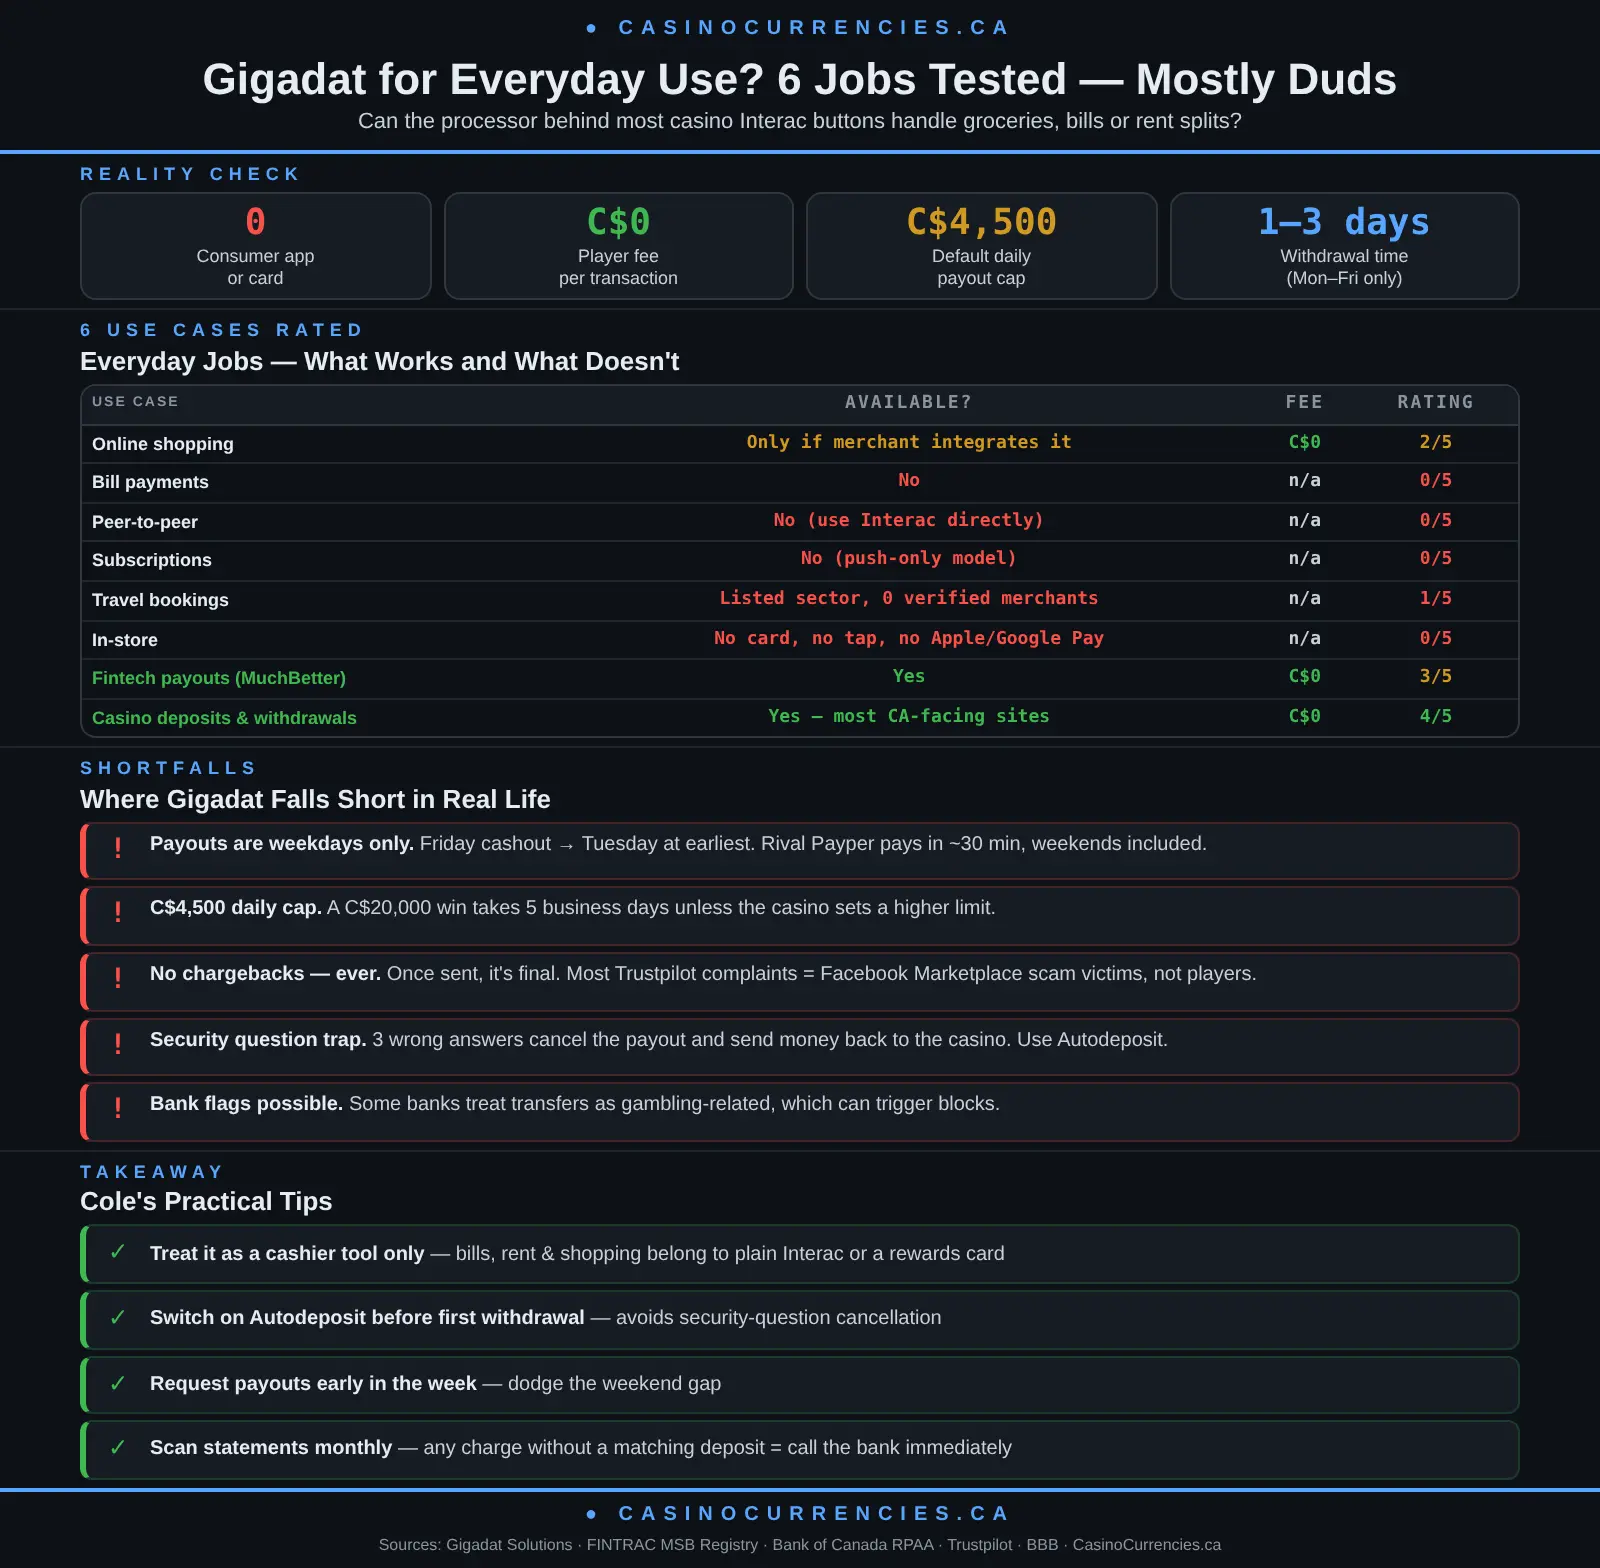
Everyday Use Cases: Available, Fees and My Rating
The ratings are mine, and they weigh availability first. “Fee” means what the processor charges the player. Bank plan fees are separate.
| Use case | Available? | Fee to the player | My rating |
|---|---|---|---|
| Online shopping | Only at merchants that integrate it; no verified big retailers | C$0 | 2/5 |
| Bill payments | No | n/a | 0/5 |
| Peer-to-peer transfers | No (use Interac directly) | n/a | 0/5 |
| Subscriptions | No (push-only model) | n/a | 0/5 |
| Travel bookings | Listed sector, no verified merchants; CAD only | C$0 if a merchant offers it | 1/5 |
| In-store | No | n/a | 0/5 |
| Fintech payouts (e.g. MuchBetter) | Yes | C$0 | 3/5 |
| Casino deposits and withdrawals | Yes, at most Canada-facing sites | C$0 (casino minimums apply) | 4/5 |
One footnote: some bank accounts charge per e-Transfer. I couldn't confirm which ones, so I'd check the account's fee schedule first.
Does Gigadat Come With Any Everyday Perks?
Not many. Here's the honest list:
- Rewards: none. No points, no cashback, no tiers.
- Cards: none. No debit, prepaid or virtual card.
- Budgeting: no dashboard, no spending categories. The bank's own app is the only record.
- Fees: C$0 to the player. Merchants pay a flat fee per transaction instead.
- Privacy: the one real perk. The payment starts inside the player's bank, so merchants never see banking details. The processor is also PCI DSS compliant and tokenizes data.
Is Gigadat Safe Enough for Everyday Money?
Mostly, with caveats. It's registered with FINTRAC as a money services business (no. M23430346, registered March 30, 2023). One registry snapshot shows an expiry of January 31, 2026, while another source says it runs to 2028 — so I'd check FINTRAC's live registry. It also applied to the Bank of Canada under the Retail Payment Activities Act on November 1, 2024. That application was still pending as of September 2026, though I couldn't check the live registry myself.
The bigger catch is no chargebacks. Once money is sent, it's final, and that protects merchants, not players. Most of the processor's Trustpilot reviews come from Facebook Marketplace scam victims, not casino players. In one BBB reply, the company said a victim had approved a Request Money that paid into a merchant deposit.
A Gigadat payment in banking history with no casino deposit behind it is a red flag. I'd call the bank first, then the Canadian Anti-Fraud Centre at 1-888-495-8501. After that, send the Interac reference number to csr[at]gigadatsolutions.com.
Where Does Gigadat Fall Short in Real Life?
- Acceptance gaps: outside casinos and a fintech payout or two, it's close to invisible.
- Payout days: Gigadat withdrawal time is 1–3 business days, Monday to Friday only. A Friday-evening cashout lands Tuesday at the earliest. Rival Payper pays in about 30 minutes, weekends included.
- Daily caps: the default payout cap is C$4,500 per player per day. A C$20,000 win takes five days unless the casino sets a higher limit.
- Deposit limits: the default range is C$30–C$7,500 per deposit, though casinos can set their own minimum. Banks add caps too — roughly C$3,000 per transfer and C$10,000 per 24 hours, varying by bank.
- The security question: three wrong answers cancel a payout and send the money back to the casino. Autodeposit skips the question entirely.
- Bank flags: one source says some banks treat these transfers as gambling-related, which can trigger blocks.
- No reversals: a pending e-Transfer can be cancelled, but an accepted one is gone.
Also worth knowing: anyone still hunting for an Interac Online casino is chasing a ghost. Interac shut that service down on October 31, 2024. Today it's e-Transfer and Request Money or nothing.
Gigadat vs iDebit for everyday money
iDebit at least gives a separate balance, which feels more like a wallet. But third-party sources put its fees at about C$1.50 per bank-funded deposit and C$2.00 to move money back to the bank. I couldn't check iDebit's official fee page, so treat those numbers with care. Neither replaces a debit card for daily spending. For casino play, I'd still take the C$0 route.
Verdict: Who Should Lean on Gigadat Beyond the Bankroll?
Since there's no account to keep, “keeping” it really means knowing when it's the right button. Here's my split:
- Worth using beyond gambling: MuchBetter users pulling money out, plus anyone whose merchant offers it at checkout and who wants banking details kept away from that merchant.
- Bankroll only: everyone else. Bills, rent splits, subscriptions, travel and in-store spending belong to plain Interac, debit or a credit card with real rewards.
- Casino players: it's the default pick — C$0 player fees, CAD only, instant deposits and usual bonus eligibility. High rollers should mind the weekday-only payouts and the C$4,500 daily cap.
Truth is, the cashier is where this thing earns its keep. My Gigadat casino Canada shortlist flags each site's minimums, payout caps and real-world speed.
My Practical Takeaway
- Keep plain Interac e-Transfer in the banking app for people, bills and everyday shopping.
- Treat this processor as a cashier tool, and pick a casino with fast, high-limit payouts.
- Switch on Autodeposit before the first withdrawal, so a typo can't cancel it.
- Request payouts early in the week to dodge the weekend gap.
- Scan statements monthly. Any charge from this processor without a matching deposit means a call to the bank.